
What Drives Redevelopment Property Valuation?

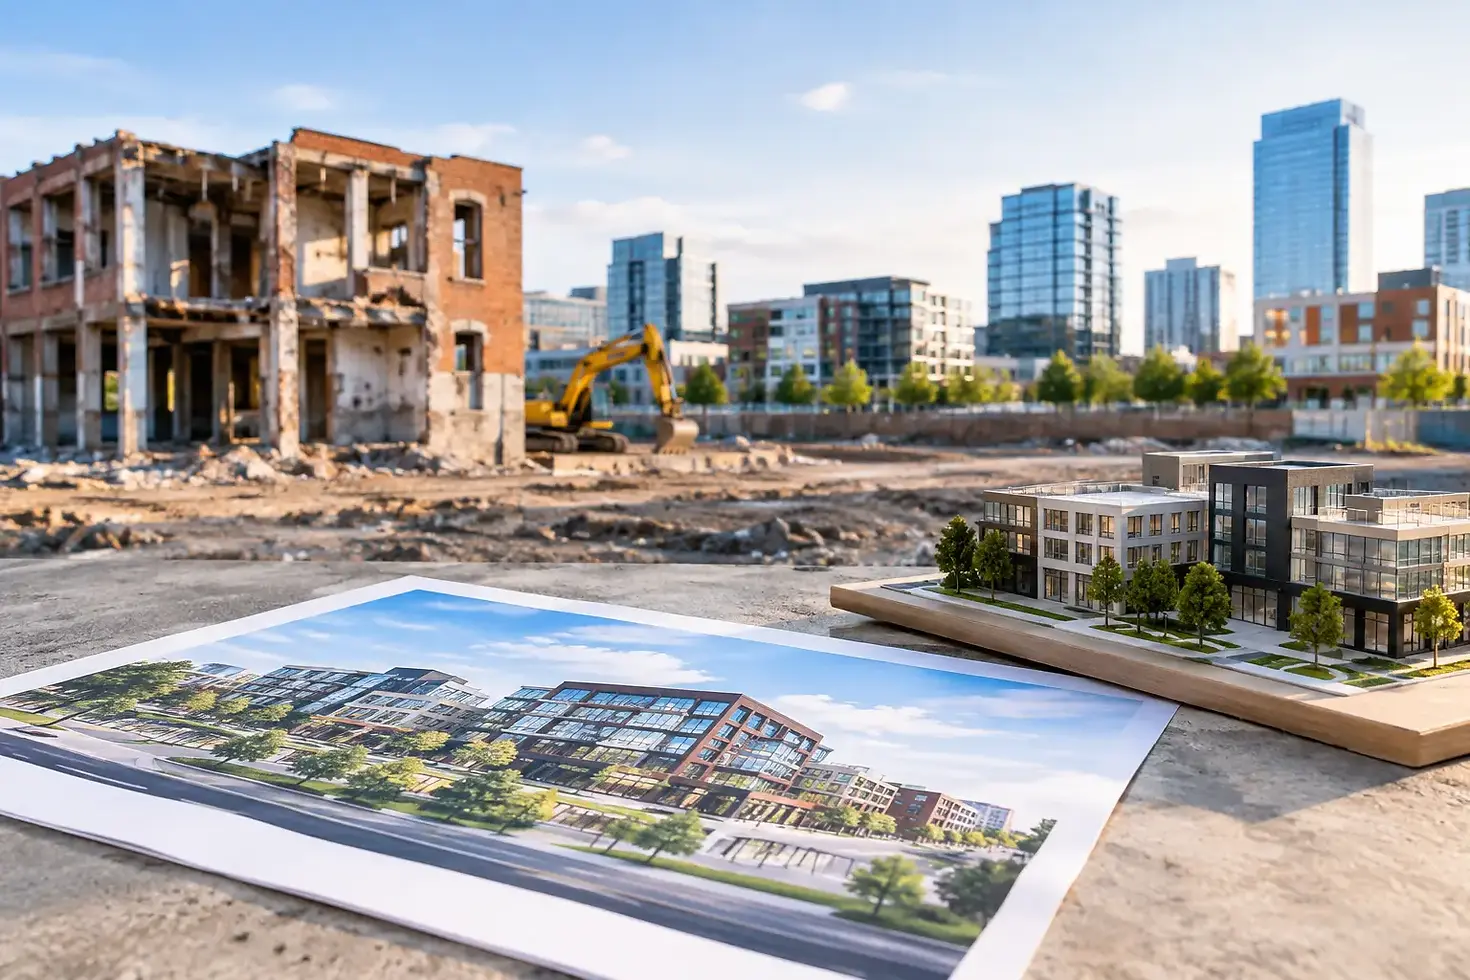
An aging commercial building on a well-located parcel may be worth less for its current income than for the future use a buyer can legally and feasibly create. That distinction is the center of redevelopment property valuation. Owners who rely only on the existing improvements, current lease income, or a nearby comparable sale can leave substantial value unrecognized - or pursue a price the market cannot support.
A disciplined valuation begins with the site, then tests the development case against entitlement, physical constraints, market demand, capital requirements, and execution risk. The objective is not to produce an optimistic number. It is to establish a credible value range and a sale strategy that gives qualified buyers enough confidence to compete.
Redevelopment Property Valuation Begins With the Site
For a redevelopment asset, land often carries the primary economic value. Existing improvements may generate income, provide interim utility, or create a demolition obligation. They do not automatically define the asset's highest-and-best-use.
The first question is direct: what can this site support today under applicable zoning, land use controls, and development regulations? The answer requires more than reading a zoning label. Parcel dimensions, access, frontage, setbacks, utility availability, environmental conditions, stormwater requirements, parking standards, overlay districts, and concurrency obligations can all affect the usable development envelope.
A site with favorable location characteristics but limited access may not command the same value as a similar-sized parcel with multiple points of ingress and established utility capacity. Likewise, a parcel with an older commercial structure may appeal to an owner-user, an income buyer, or a developer. Each audience will analyze the asset differently, and the valuation must account for those competing use cases.
Existing Improvements Are Not Automatically an Asset
An existing building can contribute value when it produces dependable income, can be adapted to a future use, or gives a buyer time to plan a larger project. In other situations, it creates demolition cost, environmental exposure, tenant coordination issues, or an obstacle to site design.
This is why replacement cost is rarely the right starting point for a redevelopment assignment. A buyer does not pay for historical investment simply because it occurred. The buyer evaluates what remains useful and what must be removed before the site can achieve its intended use.
Highest-and-Best-Use Must Be Tested, Not Assumed
Highest-and-best-use analysis is central to a value-driven disposition process. It identifies the use that is physically possible, legally permissible, financially feasible, and maximally productive. Those tests must be applied in sequence. A use can be attractive in concept yet fail because of entitlement limitations, construction economics, or insufficient end-user demand.
For example, a higher-density plan may appear to create more residual land value than a lower-intensity alternative. But if that plan requires a lengthy approval process, off-site infrastructure contributions, substantial parking accommodations, or uncertain agency support, a buyer may discount the land heavily. A smaller by-right project can sometimes produce a stronger, more reliable land value because the path to execution is clearer.
The analysis should consider both current allowances and reasonable entitlement upside. Treating speculative future approvals as if they were already secured can weaken credibility during buyer negotiations. At the same time, ignoring a realistic rezoning, comprehensive plan amendment, or assemblage opportunity can understate the property's strategic value. The proper treatment depends on the evidence, the anticipated approval path, and the buyer universe most likely to pursue it.
Entitlement Status Changes Both Value and Risk
Entitlements are not merely a planning issue. They are a valuation issue because they determine what risk a buyer must accept after closing.
A site with approved plans, vested rights, completed studies, and a defined development program may attract buyers willing to pay for reduced uncertainty. A site with only preliminary concepts may still be valuable, but buyers will generally seek a discount for the time, capital, and approval risk they must carry. Neither condition is inherently better for every owner. Advancing entitlements can increase marketability, yet it also requires cost, time, and exposure to changing market conditions.
Owners should understand precisely what has been approved, what remains discretionary, and whether prior approvals are transferable, active, or approaching expiration. Supporting materials matter: surveys, environmental reports, traffic studies, utility correspondence, site plans, and agency communications can either reduce buyer diligence concerns or expose unresolved issues early.
In Florida and Georgia, entitlement outcomes can vary substantially between jurisdictions and even between submarkets. Local development policy, infrastructure capacity, growth patterns, and political conditions can influence both the probability and timing of an approval. Valuation should reflect that local reality rather than applying a generic land price across different regulatory environments.
Feasibility Separates Potential From Price
A redevelopment concept has value only if a capable buyer can make the economics work. This is where residual land analysis becomes useful. The buyer estimates completed project value, subtracts hard and soft costs, financing, carrying costs, required return, contingencies, and profit, then determines what remains available for land acquisition.
That calculation is sensitive to several variables. Rent or sale assumptions, construction pricing, interest rates, absorption, operating costs, parking requirements, and impact fees can each change the residual land value. A concept that supported a particular price eighteen months ago may no longer support it under current capital-market conditions.
Comparable land sales remain relevant, but they should be interpreted carefully. A reported price may reflect superior zoning, unusual seller financing, an assemblage premium, a completed entitlement package, or a buyer with a strategic reason to pay above ordinary market value. Good valuation does not merely collect transactions. It explains why a transaction is comparable and where its differences require adjustment.
The Buyer Universe Influences Value
The likely buyer is part of the valuation. An owner-user may focus on location, functionality, and occupancy timing. A regional developer may emphasize approved density, construction economics, and exit demand. A national investor may require scale, institutional documentation, and a particular return threshold.
Each buyer group can assign a different value to the same parcel. That does not mean every stated interest level is equally meaningful. A disciplined process identifies the groups most capable of acting, presents the development thesis with supporting evidence, and protects the seller from being anchored by early, conditional proposals.
Confidentiality can also affect strategy. Some owners need to avoid disrupting tenants, employees, adjacent stakeholders, or operating plans. In those cases, controlled outreach to a qualified buyer set may preserve value better than broad market exposure. Other assignments benefit from a wider competitive process because the highest-and-best-use is clear and demand is deep. The correct approach depends on the property and the owner's priorities.
A Seller-First Valuation Process
A useful valuation should lead to decisions, not simply a number in a memorandum. The process should establish the property's current condition, development potential, entitlement position, likely buyer segments, and a defensible range of value. It should also identify the work that could improve sale readiness before the property is offered.
That may include confirming zoning interpretations, updating a survey, organizing diligence materials, resolving a title issue, obtaining preliminary utility information, or preparing a concise land-use narrative. Not every property warrants additional pre-sale investment. If the market can price a known risk efficiently, spending time to eliminate it may not create a sufficient return. If a risk is likely to cause retrades or deter qualified buyers, addressing it can be worthwhile.
Exclusive seller representation provides needed alignment in this stage. The advisor's role is to protect the owner's position, test the value proposition independently, and manage negotiations against the actual development economics buyers will use. Diaz Commercial approaches redevelopment assignments with that seller-first discipline, combining valuation, land entitlement analysis, and controlled disposition strategy.
Timing Is Part of the Valuation Decision
Market timing is not limited to whether prices are rising or falling. It includes the availability of development capital, construction costs, competing site inventory, municipal planning activity, and the owner's own holding requirements. A near-term sale may be appropriate when buyer demand is active and the entitlement story is sufficiently clear. A delayed sale may be justified when a defined entitlement milestone is likely to reduce uncertainty or broaden the buyer pool.
The critical point is to make that decision from evidence, not attachment to a prior value expectation. A redevelopment property should be positioned according to what informed buyers can support now, adjusted for the specific steps that can credibly change the asset's future value.
For owners of underutilized commercial assets, the right valuation is not a static opinion of what stands on the site. It is a disciplined assessment of what the property can become, what it will take to get there, and how to convert that potential into a controlled sale process.


Comments